Gresham House
Specialist asset management
September 2026
September 2026
Institutional portfolios are far more diversified by label than they were three decades ago, incorporating alternatives and private assets for up to 50% in allocations, significantly including a variety of private asset exposures, such as private equity, core-to-value-add infrastructure and real estate.
However, portfolios typically remain exposed to the same underlying return drivers that affect equities and bonds, interest rates, liquidity and short-term market sentiment. In 2022 this became clear when rising rates pushed equities and bonds lower together and a traditional 60/40 portfolio fell by 16–17%.
For long-term investors, natural capital speaks directly to this concentration. Its returns are driven by biological growth, land productivity and environmental markets rather than by interest rates or market sentiment, so it has a genuinely low correlation with a conventional portfolio and even a modest allocation can improve the portfolio’s risk-adjusted return.
Read our latest report on why natural capital should be treated as a distinct real assets allocation, not simply a thematic tilt.
In brief:
- Where to allocate:
Primarily Real Assets, sitting alongside real estate and infrastructure; increasingly, allocations are held in a dedicated natural capital or “natural resources” allocation. - How we define natural capital:
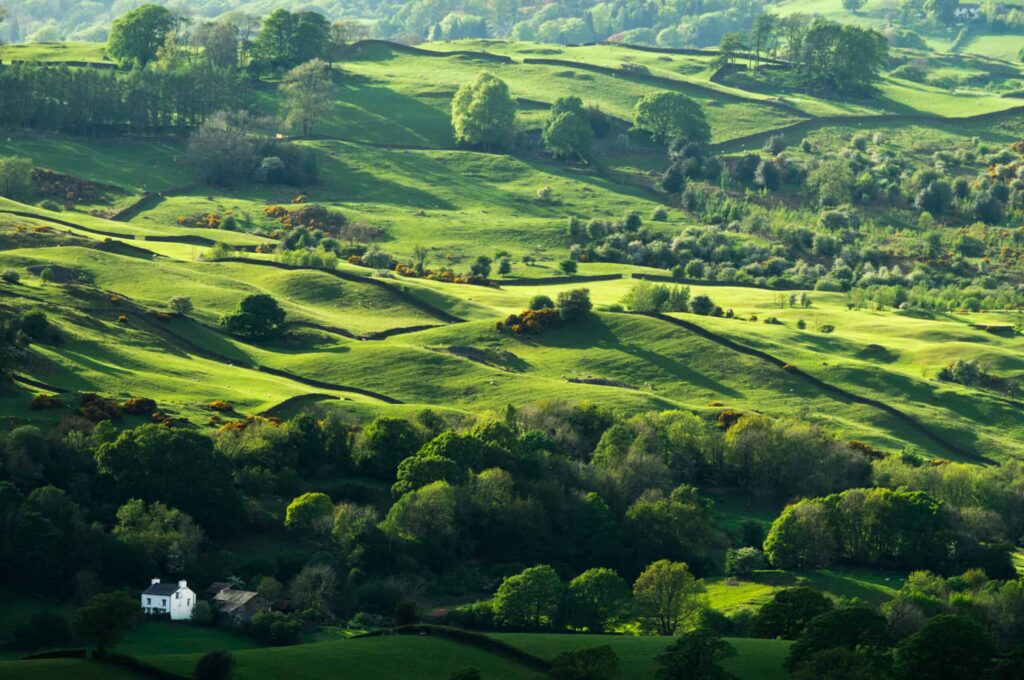
Three land-based sub-strategies, sustainable forestry (timber), agriculture, and nature markets (carbon and biodiversity credits, including Biodiversity Net Gain). - Why investor portfolios can benefit:
Differentiated return drivers and low-to-negative correlation to a diversified portfolio mean even a 10% allocation improves risk-adjusted return (Sharpe +7.4%, Sortino +32.5%), lifts the diversification ratio (+7.2%) and reduces equity beta by 13%. - What is an appropriate allocation:
The portfolio benefit is front-loaded, a 10% allocation captures 64% of the average maximum improvement (86% by 15%, 97% by 20%), making ~10% a pragmatic entry point. Within that we focus around an allocation base case of 65% forestry / 25% agriculture / 10% nature markets. - The risks to manage:
Natural capital carries physical, market, regulatory, operational and currency risks. These differ from mainstream financial-market risks and are manageable through diversification across geography, species and crop type, conservative underwriting, active on-the-ground management, and appropriate insurance and governance.
Media enquiries
KL Communications – gh@kl-communications.com
40 Queen Street, London EC4R 1DD
+44 (0) 20 3995 6671
www.kl-communications.com